
Learn · The MoneyYogi Method
A step-by-step blueprint to get out of your own way and automate your wealth.
If you have ever stared at a messy bank balance, a pile of receipts on your desk, or an uninvested brokerage account and felt totally frozen, you are not alone.
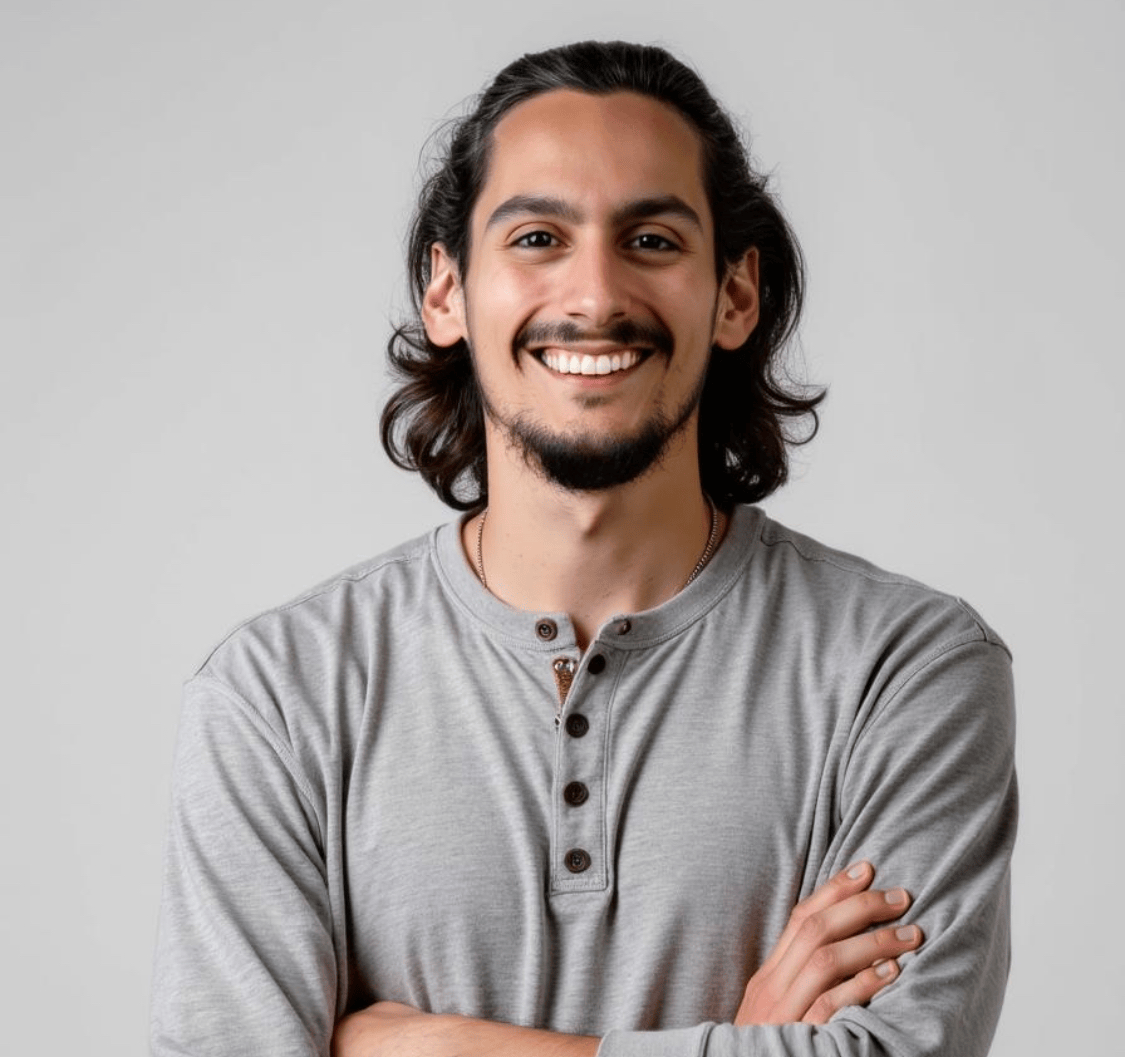
Joshua Humada, CRPC®, AAMS®
Founder, MoneyYogi
Most people think they have an information problem. They tell themselves, "I just need to find the right book, the right spreadsheet, or the right YouTube video, and then I will finally get my act together." But when they sit down to do the work, their shoulders tense up, their stomach drops, and they end up closing the laptop and walking away.
The reason is simple: when you try to solve an emotional, subconscious reaction with raw logic and tactics, logic loses every single time.
For many people, money is the number one source of stress in the country. It does not matter how much money someone makes. In my work helping people with their finances, I see folks making six or seven figures who struggle with the exact same knot in their stomach as someone just starting out. When you are under intense stress, your body slips straight into survival mode. Your nervous system treats that unpaid bill or confusing 401(k) screen like a threat in the room with you. In that state, it is very challenging to make sound, long-term decisions.
If you want to build lasting wealth, you have to work in the right order:
- Ground: Your Physical State
- Rewire: The Money Blueprint
- Automate: Your Financial Strategy
- Align: Your Regular Recurring Money Checkup
When you respect that sequence, everything changes.
Phase 1: Ground (Your Physical State)
Before you open a single account or look at a single number, you have to get your body out of survival mode.
Most people do not realize that their physiology runs the show. When your heart is racing, your breathing is shallow, or your neck is rigid, your brain is getting loud signals that you are not safe. Trying to make smart, forward-looking decisions about your future when your body feels under attack is nearly impossible.
The goal here is simply to encourage you to begin learning about your body and discovering what actually makes you feel better and more centered.
Everybody is different, but here are a few simple ways to reset your physical baseline:
- Check your posture. If you are slumped over a screen or hunched up in a chair, sit tall or stand up. Roll your shoulders back and open up your chest. Your posture directly affects how you feel.
- Do some box breathing. Inhale slowly through your nose for four seconds, hold your breath for four seconds, exhale gently through your mouth for four seconds, and hold empty for four seconds. Repeating this box breathing cycle even three or four times calms your nervous system down quickly.
- Do some physical activity or maybe some yoga stretches. Step away from your desk. Go on a quick five-minute walk, or do some light stretching to shake the tension out of your body. Physical movement breaks the mental loop immediately.
- Get outside and get some sunshine early in the morning. Stepping outside for a few minutes of morning sunlight is one of the simplest ways to help your body feel awake, settled, and ready for the day.
- Drink water and stay hydrated. Dehydration quietly raises your heart rate and mimics physical anxiety. Drinking some water helps ground you right in the room.
- Notice your tension spots. Pay attention to where you hold stress. Is your jaw clenched? Are your eyebrows scrunched up? Are your hands balled up? Let them go on purpose.
Pay attention to what works for you. When your body feels grounded and centered, your brain comes back online. You are no longer reacting from panic. Now you can actually think.
Phase 2: Rewire (The Money Blueprint)
Once your physical state is settled, it is time to look at the programming running in the background.
There is a simple formula for how our lives work:
Thoughts lead to feelings. Feelings lead to actions. Actions produce your results.
If you do not like the results in your bank account, you cannot just force yourself to take new actions while keeping the exact same thoughts. You have to trace it all the way back to the root: what you actually believe about money.
Where your story came from
Here is what you have to remember: your original money story was written when you were a kid.
Up until about age six or seven, your brain operates like a complete sponge. You did not have a critical filter yet. You were pure awareness, taking in literally everything around you. Advertising was hitting you. School was hitting you. Family dynamics, church, friends, and the community you grew up in were all pouring information directly into your subconscious mind.
Depending on who you were around and what you saw, you absorbed specific lessons about money without even knowing it:
- If you grew up around constant arguing over bills, your subconscious learned that money equals fighting, danger, and tension.
- If you were around people who constantly said, "We cannot afford that," or "People with money are greedy and dishonest," you absorbed the idea that wealth is somehow bad or impossible for you.
- If money was used as an emotional band-aid to celebrate or soothe sadness, you learned to spend whenever your feelings get loud.
Those early memories formed a hidden financial blueprint inside you. A belief is simply a thought you have practiced over and over until you hold it as true. Beliefs are not universally right or wrong, true or false. They are just strong opinions you have carried for a long time.
As the old saying goes, we do not see the world as it is. We see the world as we are.
To find your current beliefs about money, you do not need to guess. Just look at your life. You will always act, or fail to act, in accordance with your predominant beliefs, and those actions create your results. Henry Ford put it simply: "Whether you think you can, or you think you can't, you're right."
How to install a new blueprint
If your current story is not serving you, you can rewrite it. You hold the pen now.
- Write down your honest money thoughts. Grab a blank sheet of paper and finish these sentences without editing yourself:
- "Money is..."
- "People with lots of money are..."
- "Having money makes me feel..."
- "If I become wealthy, my family or friends might think..."
- Examine the list. Look at what showed up. Ask yourself: "Is this genuinely a universal truth, or is this just an old opinion I picked up when I was seven years old?"
- Choose your replacement thoughts. For every disempowering belief, write down an empowering truth that you want to live by. For example:
- Old: "There is never enough money to go around."
- New: "Money is a tool that flows through my life, and I am fully capable of managing it with clarity."
- Practice the new story. Your old blueprint took years of repetition to build. Your new one requires repetition too. Remind yourself of your new thoughts daily, especially right before you look at your finances.
Phase 3: Automate (Your Financial Strategy)
Once your physical state is grounded and your story supports where you want to go, you are ready for the strategy.
This is where most people get tripped up: they try to start here. But when you build your strategy after mastering your state and your story, it is not scary anymore. It just becomes practical plumbing.
We do not need 50 complicated spreadsheets. We need a clean, automated system where every single dollar has a clear job the moment it lands, long before your impulses get a vote and long before marketers decide what to do with that cash for you.
We start with cash flow: what is coming in and what is going out.
If you are a business owner: start here
(If you do not own a business or do freelance work, you can skip straight to the personal section below.)
If you run a company, you cannot blend your business cash and your personal life together. That is the quickest path to chronic stress.
We recommend setting up five distinct business bank accounts, loosely built around the proven Profit First framework:
- The Business Inbox Account (Checking). Think of this like your physical mail inbox. Every dollar of revenue, client payments, customer transactions, and commissions lands here first. Crucial rule: the Inbox is strictly a sorting station. It is meant to be emptied on a regular schedule, not used to store cash or pay bills.
- The Operating Expense Account (Checking). This account pays for the day-to-day cost of running your business: software, contractors, inventory, payroll, and supplies. When money is sorted out of your Inbox, a set portion moves here.
- The Tax Bucket (High-Yield Savings). Every time revenue lands, a portion goes straight into a dedicated tax savings account. Do not guess this number on a whim. Talk with your CPA or financial advisor to look at your past returns and establish a realistic percentage. You will not get it exact down to the penny, but you will never be caught empty-handed when quarterly estimated taxes come due.
- The Profit & Buffer Account (High-Yield Savings). This account ensures your business is profitable from day one. You tuck a portion away here immediately. It acts as a safety buffer for the business, can be used for quarterly owner profit distributions, or can sit safely as capital for future strategic growth.
- The Owner Pay Account (Checking). This is the account that pays you. Even though your business revenue might come in at random times throughout the month, money accumulates in this bucket so you can pay yourself on a predictable rhythm, like the 1st and the 15th of every month. It turns chaotic business income into a steady, reliable salary.
The automation tool
The one modern tool I have found that handles this kind of automated business logic very cleanly is a modern business bank called Mercury.
Mercury allows you to create multiple checking and savings accounts under one login without extra fees, and it has built-in auto-transfer rules. You can set up logic so that whenever money arrives in your Inbox, it automatically splits and moves into your Operating Expenses, Taxes, Profit, and Owner Pay buckets. That takes the willpower and daily friction out of the equation completely.
The personal account setup
Whether your income comes from a traditional W-2 job or from your business Owner Pay transfers, it now flows into your personal system.
Just like the business side, we give every dollar a specific home:
- The Personal Inbox (Checking). All personal income lands here first. Just like the business inbox, this is a sorting hub, not a holding tank. You do not spend out of this account.
- The Necessities & Operating Account (Checking). This pays for your baseline living costs: rent or mortgage, groceries, utilities, insurance, gas, and standard recurring bills.
- Separate Play Accounts (Checking). This is essential. If you manage money with a spouse or partner, you should each have your own separate play account with its own debit card. There is zero guilt and zero need to explain what you buy with this money. Its entire job is to let you enjoy your life, grab dinner, buy clothes, or treat yourself without feeling like you are taking away from the household.
- Long-Term Savings for Spending (Savings). These are short- to medium-term goals. It is money you are planning to spend eventually, just not this month. That includes your emergency cushion, money for an upcoming vacation, a car repair fund, or extra cash set aside to pay down a specific debt faster. You can have multiple sub-accounts here for different goals.
- The Financial Freedom Account (Investment / Custodial). The rule for this account is strict: you do not touch this money. Ever. You do not spend out of this bucket. The purpose of this account is to build a base of capital you never touch, so you can eventually live off the interest and cash flow it produces. This is your cow. You drink the milk, but you leave the cow alone. (We will be diving much deeper into this specific blueprint in our upcoming book on financial freedom.) The idea is to acquire long-term, appreciating assets that produce cash flow or have the ability to do so down the road. Keep it simple. Never invest in things you do not understand, and hold a diversified mix of assets. Maybe you like index funds and the stock market, or maybe you prefer real estate, land, or private businesses. The specific vehicle matters far less than building the disciplined habit of regularly setting money aside into assets that have real long-term potential to grow.
- The Education & Growth Account (Savings / Checking). This is for reinvesting directly back into yourself: books, courses, coaching, seminars, or learning high-value skills. Managing the money you have is important, but growing your earning potential is the fastest lever to build wealth. This account funds that growth.
- The Give Account (Optional Savings / Checking). If giving is an important part of your values, carve out a dedicated bucket for charitable donations, community support, or helping family.
When your money hits your Personal Inbox, automated transfers move your chosen amounts into each of these accounts. Within minutes of getting paid, your bills are covered, your taxes are safe, your future is funded, and you know exactly how much guilt-free money you have left to enjoy.
Phase 4: Align (Your Regular Recurring Money Checkup)
Once your plumbing is built, you do not need to obsess over your money every day. In fact, checking your accounts constantly is usually just anxiety masquerading as productivity.
Instead, establish a regular, recurring money checkup. Pick a cadence that works for you, sit down with a clear head, and spend ten to fifteen minutes reviewing your system.
Here is what you actually look at during your checkup:
- Check your buckets. Look at the accounts you set up. Is money flowing where it is supposed to go? Are the automatic transfers sorting your cash properly and applying it toward the goals you have established?
- Review your cash flow for the month. Look at what came in and what went out. Are you cash flow positive or cash flow negative? Check on upcoming bills to see what is scheduled to leave your accounts over the next few weeks so nothing catches you off guard.
- Pick one or two actionable improvements. Ask yourself: "What are one or two things I can do between now and my next money checkup to improve my financial knowledge or improve my situation?" Maybe that means canceling an unused subscription, reading a chapter of a finance book, or bumping up your transfer to your Financial Freedom account by one percent.
That is it. You review the buckets, check your cash flow, choose your next small adjustment, and get back to living your life.
The Real Order of Wealth
Building financial peace is not about having ironclad willpower or memorizing complicated financial jargon. It is about working with human nature instead of fighting it.
When you try to start with numbers while your body is panicked and your mind is running an old, fearful story, you will stay stuck. But when you follow the blueprint:
- Master your physical state first.
- Rewrite your money story second.
- Automate your strategy third.
- Hold your recurring checkup fourth to inspect your system and take action.
The friction disappears, the old survival mode shuts off, and genuine financial peace takes its place. Master your physical state first, numbers second.
Want help walking through this?
If you'd rather not set this up alone, I work one on one with a small number of people. We can look at your buckets together and figure out what makes sense for your situation. Your first call is a working session, not a sales pitch.
Book a callAdvisory services are provided by Boundless Wealth LLC d/b/a Money Holistics. MoneyYogi LLC provides software only and does not provide investment advice.
Educational disclosure: This article is for educational purposes only and does not constitute personalized investment, legal, or tax advice. All investing involves risk of loss. Always consult with a qualified financial advisor, CPA, or attorney regarding your specific situation.
About the author
Joshua Humada, CRPC®, AAMS®
Joshua Humada is the founder of MoneyYogi and an investment advisor representative of Money Holistics, an investment advisor. He works one on one with a limited number of clients and built MoneyYogi to give everyone else the same calm, complete view of their money.
See every bucket in one place.
Connect your accounts once and watch your cash flow and your buckets in one calm view.
Start your trial